Skip to content
From Legislation to Implementation: What the FDIC’s Reciprocal Deposit Rule Means for Banks
R&T Logo, Blue
  • Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars
Contact Us
Contact Us
  • Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars
Contact Us
Back to News & Insights

Trust Company Cash in a Shifting Rate Cycle: Why Insured Sweeps Are Emerging as the Standard

Updated October 2026 (originally published December 2, 2025)

trust company cash in a shifting rate cycle: why insured sweeps are emerging as the standard

Money market funds held $7.89 trillion for the week ending September 30, 2026 (Investment Company Institute). Their rates track the Federal Reserve’s target range, which has now moved through a full cycle. The range peaked at 5.25-5.50% in 2023, fell through the cuts of 2024 and 2025, and rose again in September 2026, to 3.75-4.00% (Federal Reserve).

For trust companies and banks with trust departments, each turn brings the same customer questions: why did the rates change, and are my trust customers’ deposits insured?

Customers Expect More Than Rates

Rates draw cash into money market funds. However, trust company and bank trust department customers expect more from their cash than rates.

For most, the priorities are clear:

  • Principal protection

  • Daily liquidity1

  • Transparency and control

Insured cash sweep programs help institutions meet those customer expectations across rate cycles, without the reinvestment risk that comes with chasing money fund rates.

Money Market Fund Assets Keep Climbing

Total financial assets, quarter-end, Q2 2020 to Q2 2026
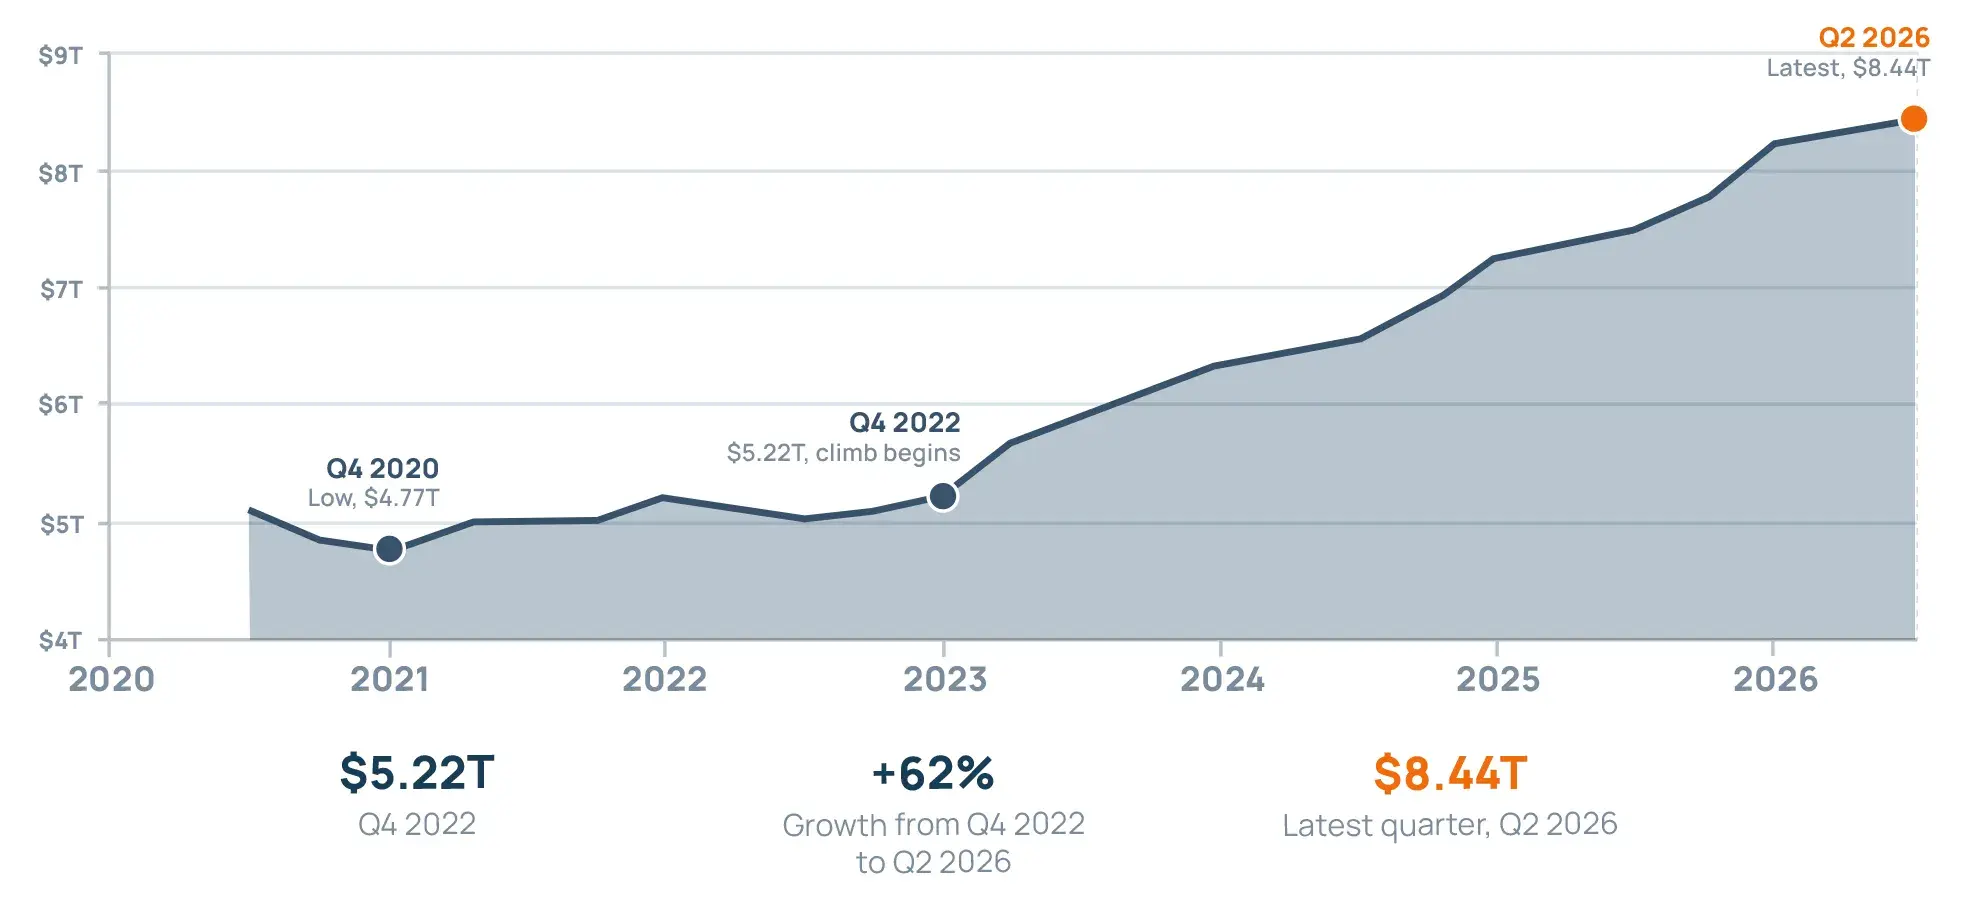
A line graph titled 'Money Market Fund Assets Keep Climbing' tracking total financial assets from Q2 2020 to Q2 2026. The chart shows a low of $4.77 trillion in Q4 2020, followed by a climb beginning at $5.22 trillion in Q4 2022, and reaching $8.44 trillion in the latest quarter, Q2 2026. Callout text below the chart highlights a 62% growth from Q4 2022 to Q2 2026. The data is sourced from the Federal Reserve Board via FRED as of October 27, 2026.

Federal Reserve Board, Financial Accounts of the United States (Z.1), money market funds’ total financial assets, via FRED (series MMMFFAQ027S), as of October 27, 2026. Quarter-end values.

Uninsured Balances Keep Growing

In the second quarter of 2026, estimated uninsured domestic deposits rose $317.4 billion and drove the quarter’s deposit growth (FDIC, Quarterly Banking Profile, Q2 2026). For the full breakdown, see Insured Trust Deposits: Strategies for Trust Organizations.

A large customer balance at a single bank is the simplest place for that exposure to build. Through the Demand Deposit Marketplace® (DDM®) program, a trust company or bank with a trust department can spread its customers’ cash across a network of FDIC-insured receiving banks. Customers get access to expanded deposit insurance coverage through those participating banks, while maintaining their primary trust company relationship.

Money Market Fund Uncertainty

History shows why trust companies and bank trust departments should not rely on money market funds alone:

  • 2008: The Reserve Primary Fund “broke the buck” on September 16, 2008, the day after Lehman Brothers filed for bankruptcy, when its net asset value fell below $1 per share (SEC).

  • 2020: On March 18, 2020, the Federal Reserve launched the Money Market Mutual Fund Liquidity Facility to help money market funds meet redemption requests from investors (Federal Reserve).

  • 2023: The SEC rewrote the rules for money funds. Institutional prime and institutional tax-exempt funds must now charge a liquidity fee when daily net redemptions exceed 5% of net assets, and any non-government fund can impose a discretionary fee. Government money market funds are exempt from the mandatory fee (SEC).

  • 2022 to 2026: Rates rose with the Fed’s increases, fell with the cuts, and moved again in September 2026.

Each cycle makes the same point: money market funds are cyclical, not structural. A money market fund does not offer customers access to FDIC insurance. Trust companies and bank trust departments need a cash option for their customers that holds up through the entire cycle.

Redefining the Standard

The measure of good cash management is shifting from institutions that solely capture the highest rates to institutions that best protect customers’ confidence.

That standard rests on four pillars:

  • Insurance: Access to expanded FDIC deposit insurance coverage up to the program limit, with no share price to fluctuate

  • Liquidity: Same-day liquidity comparable to money market funds1

  • Rates: Competitive rates that track market cycles2

  • Structure: Bank deposits spread across receiving institutions designed to stay within FDIC insurance limits


Insured cash sweep programs help institutions meet all four.3

The DDM program enables trust companies and bank trust departments to offer their customers access to expanded FDIC deposit insurance coverage through a network of receiving banks. Independent trust companies use the DDM program to place customer deposits that exceed the FDIC insurance limit for coverage, often simplifying operations while maintaining the primary relationship. Bank-affiliated trust companies and bank trust departments have an added option. The affiliated bank can act as a receiving institution under the program to receive reciprocal deposits, which can be treated as non-brokered funding within the statutory cap.4

DDM Performance and Integration

Over 1-, 3-, and 5-year periods, rates paid under the DDM program’s Institutional Rate have historically been in line with or higher than those on a basket of institutional government money market funds.*

Performance Data
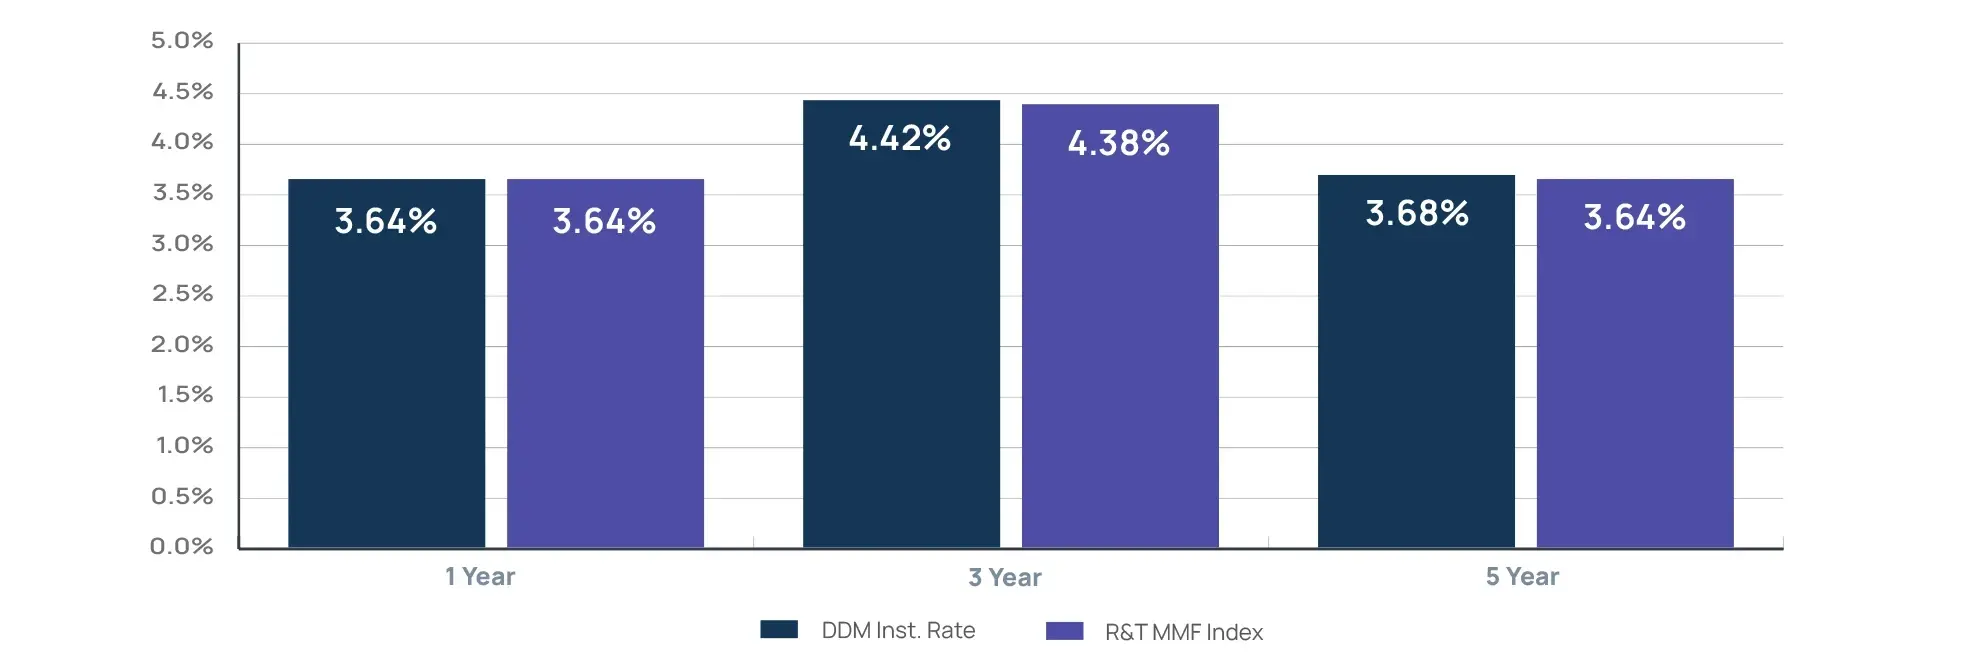
A bar chart comparing the performance of the 'DDM Inst. Rate' against the 'R&T MMF Index' across 1-year, 3-year, and 5-year periods. The 1-year returns are 3.64% for both. The 3-year returns are 4.42% for the DDM Inst. Rate and 4.38% for the R&T MMF Index. The 5-year returns are 3.68% for the DDM Inst. Rate and 3.64% for the R&T MMF Index. A footnote specifies that performance data is net of fees as of 09/30/26 and lists the 8 specific funds comprising the R&T MMF Index

*R&T MMF Index: TSTXX, DGCXX, GOFXX, GOTXX, TOIXX, FRGXX, FGTXX, NITXX. All performance data net of fees as of 09/30/26. The R&T MMF Index represents 8 commonly used MMFs, sourced from the monthly Crane Money Fund Intelligence Report.

R&T integrates with more than 50 core processors and adapts to client formats without requiring changes to existing systems, so trust companies and bank trust departments can adopt an insured cash program without disruption. The DDM program connects directly with existing trust accounting platforms, and portals, APIs, and data-exchange tools give trust officers real-time visibility into balances, transactions, and reporting, without manual workarounds.

The Imperative

Since 2022, rates have climbed, fallen, and started climbing again. For trust companies and bank trust departments, protecting principal and keeping cash available matters at every point in the cycle, and insured programs are now the baseline expectation for trust customers’ cash.3

Learn more about the DDM® program for trust companies.
Download Fact Sheet

1 Subject to R&T’s cut-off times. Under the DDM program, funds are deposited into demand deposit accounts (DDAs) or money market deposit accounts (MMDAs) at receiving banks or share draft accounts or share accounts at receiving credit unions. While customers’ funds are held in MMDAs or share accounts, the return of customers’ funds from the DDM program may be delayed as, under federal regulations, the receiving institution is permitted to impose a delay of up to seven days on any withdrawal request from an MMDA or share account.


2 While interest rates obtained on funds placed at receiving institutions under the DDM program may, under certain circumstances, outperform cash alternatives, such as money market funds, the primary objective of the DDM program is to provide customers with convenient access to expanded FDIC insurance coverage on their funds (and not for investment enhancements or higher rates of returns or profits).


3 R&T does not act in a fiduciary or trustee capacity with respect to the DDM program (the “Program”) and makes no representations or warranties that the Program satisfies any investment policy or other requirements for participating institutions. R&T does not represent that the Program enables participating institutions to meet their own fiduciary or other obligations or duties. Participating institutions are solely responsible for complying with all such policies and requirements, as well as any other applicable laws or regulations governing the deposit of specific types of funds into the Program (e.g., qualified retirement funds, free credit balances of brokerage institutions, escrow funds). R&T makes no representations or warranties that the Program complies with any such laws, except to the extent expressly set forth in the written agreements entered into between R&T and the participating institution.


4 Subject to applicable laws, regulations, rules, and limits relating to brokered deposits, including Section 29 of the Federal Deposit Insurance Act (12 U.S.C. 1831f), as amended, its implementing regulations, including 12 CFR 337.6, and applicable Call Report instructions from the FFIEC. R&T makes no representations or warranties, express or implied, with respect to an institution’s classification of deposits as brokered or not brokered. Such determination is entirely and solely the responsibility of that institution.

Previous
Next

Media Contact

Melissa Kaiser
Director, Marketing

  • 1-212-830-5242
  • mkaiser@rnt.com

Don’t Miss Out on the Latest Insights.

Follow us on: image/svg+xml

Interested?

Learn how we can help you attract, grow & retain more deposits.

Contact Us

You are now leaving rnt.com

Stay on site

OR

Click to Continue
R&T Logo, White
aba premiere partner logo
great place to work certified, OCT 2026-OCT 2027
  • 1-866-237-2752
  • info@rnt.com
  • 1370 Broadway, 17th Floor
    New York, NY 10018-7302
  • LinkedIn
  • Our Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars

R&T Deposit Networks, LLC, R&T Deposit Marketplace, LLC, R&T Deposit Solutions, LLC and R&T Deposit Programs, LLC (each d/b/a R&T Deposit Solutions), each a Delaware limited liability company, (together, “R&T”) provide administrative, recordkeeping, and/or other services to banks, credit unions, trust companies, wealth management firms, broker-dealers and other institutions with respect to deposit placement and sweep programs, including the Demand Deposit Marketplace® (DDM®), Certificate of Deposit Marketplace Exchange℠ (CDMX®) and R&T Insured Deposits℠ (RTID®) programs, as well as other services. An affiliate of R&T, Stable Custody Group II LLC (“Stable”), acts as agent of participating sending institutions under the DDM and CDMX programs.  R&T and Stable, together, “we”, “us” or “our”.  All of our services are provided subject to the terms and conditions of the written agreements and/or agency appointments between us and our clients with respect to those services, and we provide no representations or warranties, express or implied, except as expressly set forth in those written agreements and/or appointments. Click here for our legal and other disclosures. We are not an FDIC or NCUA-insured institution. FDIC insurance only covers the failure of an FDIC-insured institution. NCUA insurance only covers the failure of an NCUA-insured institution.  Certain conditions must be satisfied for FDIC and NCUA pass-through deposit insurance coverage to apply. Click here for a list of the FDIC and NCUA-insured institutions with which R&T has a direct or indirect business relationship for the placement of deposits under the DDM, CDMX, and RTID programs, and into which a participating institution may place deposits (subject to the terms of those programs and any opt-outs by the participating institution and/or its customers).  While the DDM, CDMX, and RTID programs provide access to an expanded level of FDIC or NCUA deposit insurance coverage on funds placed into the programs (subject to program terms and applicable laws, regulations and guidance, including pass-through insurance coverage requirements), the DDM, CDMX and RTID programs, themselves, as well as our other service offerings, are not insured or guaranteed by the FDIC or NCUA, are not deposits, and may lose value. We are not an affiliate of an FDIC or NCUA-insured institution, we are not an office, division, or sub-division of the FDIC or NCUA, and we are not associated with the FDIC or NCUA or office, division, or sub-division thereof. The primary objective of the DDM, CDMX, and RTID programs is to provide customers with convenient access to expanded deposit insurance coverage on their funds (and not for investment enhancements, higher rates of returns or profits). R&T®, Reich & Tang®, Demand Deposit Marketplace®, DDM®, DepositView®, CDMX®, and RTID® are registered marks and R&T DirectSM is a pending mark of R&T Deposit Networks, LLC. IDEA℠ , Certificate of Deposit Marketplace Exchange℠ , R&T Insured Deposits℠ and R&T Connect℠ are unregistered service marks of R&T Deposit Networks, LLC.

© 2026 R&T Deposit Networks, LLC

  • Privacy Policy
  • Privacy Policy – CA
  • Terms of Use
  • Legal Disclosures
  • Receiving Institution Lists
  • DDM Program Limit
  • Do Not Share My Personal Information
  • Cookies