Skip to content
From Legislation to Implementation: What the FDIC’s Reciprocal Deposit Rule Means for Banks
R&T Logo, Blue
  • Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars
Contact Us
Contact Us
  • Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars
Contact Us
Back to News & Insights

Insured Trust Deposits: Strategies for Trust Companies and Bank Trust Departments

Updated October 2026 (originally published October 27, 2025)

Rate cycles shift. However, the pressure on trust companies and trust departments of banks to protect their customers’ cash balances does not.

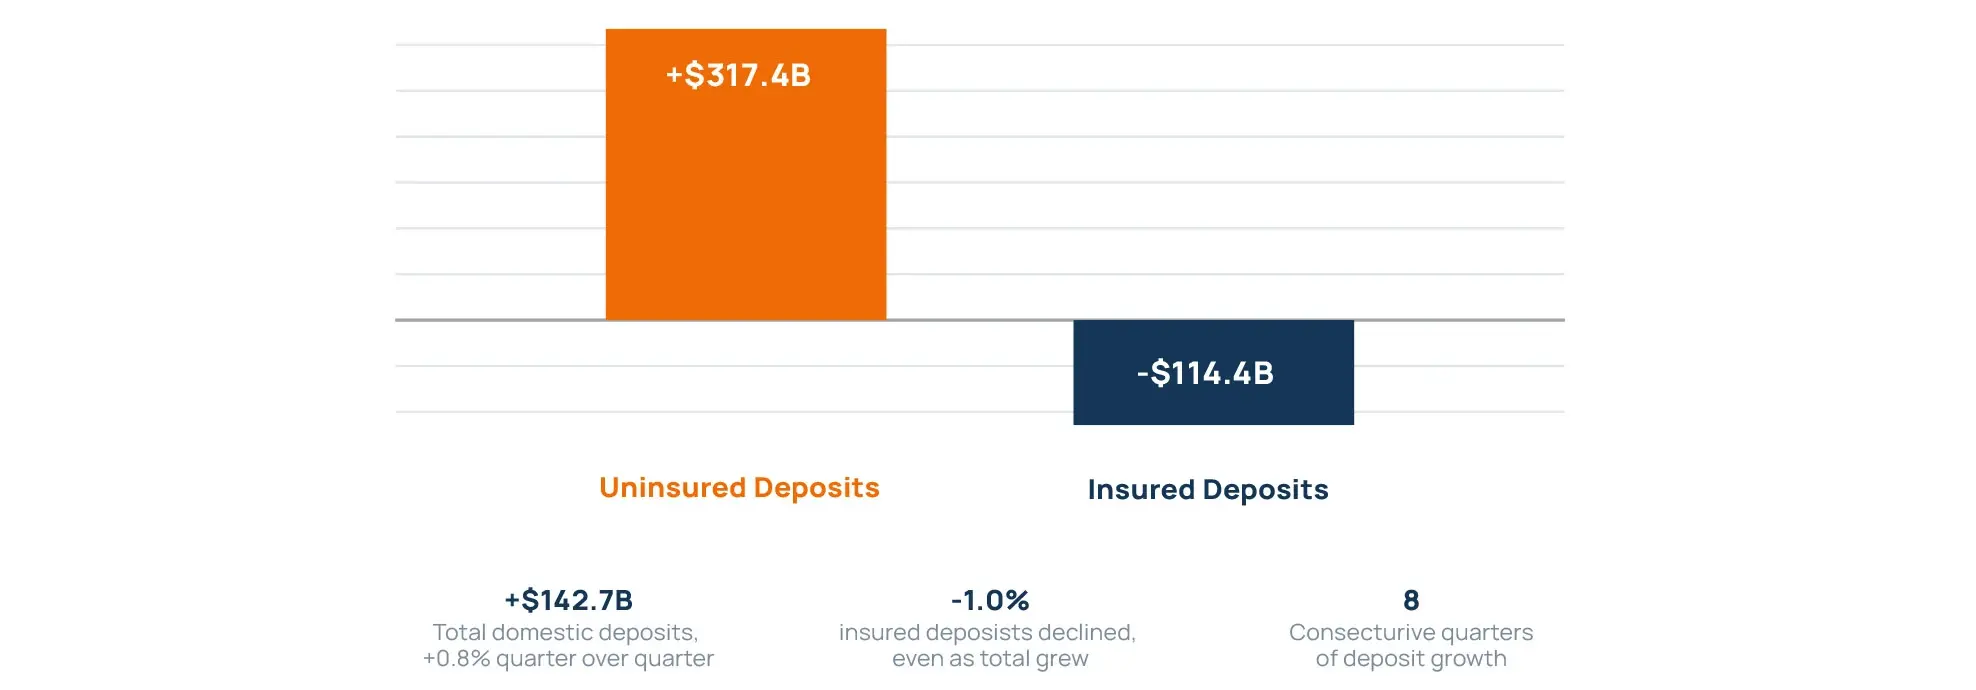
In the second quarter of 2026, total domestic deposits grew for the eighth consecutive quarter, up $142.7 billion. The growth came entirely from uninsured balances. Uninsured deposits rose $317.4 billion, while insured deposits declined 1.0%, or about $114 billion (FDIC, Quarterly Banking Profile, Q2 2026).

Q2 2026: Deposit Growth Went Uninsured

Quarterly change in domestic deposits, Q1 to Q2 2026
Graphic-1-Q2-2026-Deposit-Growth Went-Uninsured@2x.webp":
"A bar chart illustrating changes in bank deposits, showing Uninsured Deposits increasing by $317.4 billion and Insured Deposits decreasing by $114.4 billion. Additional metrics below the chart indicate that total domestic deposits grew by $142.7 billion (up 0.8% quarter over quarter), insured deposits declined by 1.0% even as total deposits grew, and the industry has seen 8 consecutive quarters of deposit growth.
Source: FDIC, Quarterly Banking Profile – Time Series Spreadsheets (Q2 2025, Balance Sheet).

Across the Rate Cycle, the Exposure Remains

Depositor behavior often corresponds to the Federal Reserve rate cycle. When the Fed pushed its target to a 2023 peak of 5.25-5.50%, rate-sensitive balances chased rates into brokered channels and money market funds. When the Fed cut rates through 2024 and 2025, the flows shifted again. In September 2026, the Fed raised rates once more, and the flows will likely follow.

Through it all, one fact remains constant. Large trust company customer balances above the $250,000 deposit insurance limit remain uninsured unless the institution acts. Q2 2026 data show uninsured deposits continuing to grow.

The Rate Cycle Keeps Turning

Federal funds target range (upper bound), quarter-end, 2022-2026
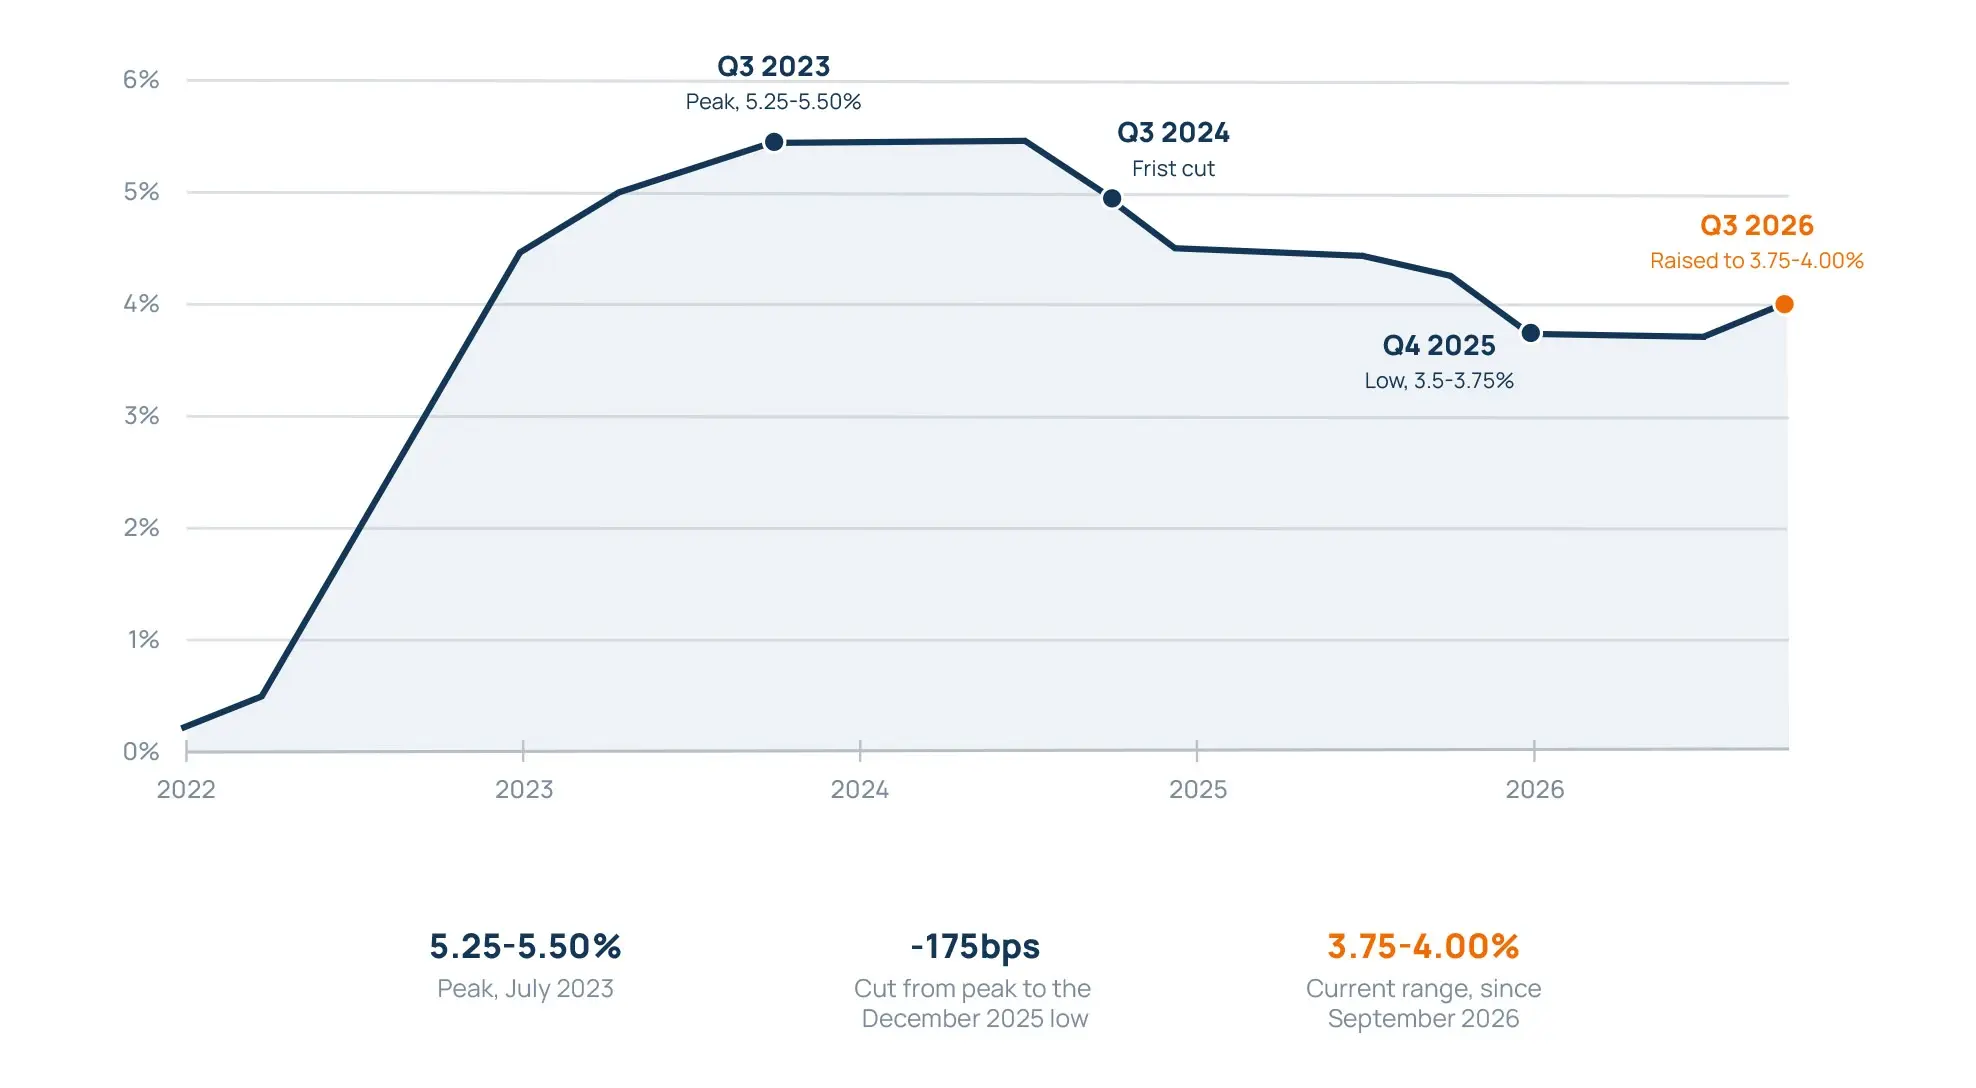
A line graph tracking an interest rate cycle from early 2022 through late 2026. The rate reaches a peak of 5.25-5.50% in Q3 2023 (specifically July 2023), experiences its first cut in Q3 2024, drops to a low of 3.5-3.75% in Q4 2025, and is raised to 3.75-4.00% in Q3 2026. Callout text at the bottom notes a 175 basis point cut from the peak to the December 2025 low, and confirms the 3.75-4.00% current range has been in place since September 2026.
Source: FDIC, Quarterly Banking Profile – Time Series Spreadsheets (Q2 2025, Balance Sheet) with rate changes over time.

Alternatives to Money Market Funds

Many trust companies and banks with trust departments rely on money market funds (MMFs) for investing fiduciary cash. MMFs are familiar and easy to administer, but some carry NAV and liquidity-fee risk, and they leave the insured-versus-uninsured question unanswered.

Cash sweep programs offer same-day liquidity and competitive rates while also providing trust customers with access to expanded FDIC deposit insurance on their funds. (For the full money-fund comparison across rate environments, see Trust Company Cash in a Shifting Rate Cycle.)

Each rate cycle teaches the same lesson. When rates rise, brokered deposits and money funds draw attention. When the cycle turns, or stress appears, insured balances regain priority. With uninsured deposits driving industry deposit growth, insured cash positions stand out as stable, defensible funding.

R&T Deposit Solutions for Trust Companies

The Demand Deposit Marketplace® (DDM®) program helps trust companies manage their customers’ cash and gives their customers access to expanded FDIC deposit insurance coverage, without relying on money funds.

For trust companies, R&T’s solutions provide:

  • Access to expanded FDIC insurance coverage on large balances.

  • Same-day liquidity comparable to money funds.1

  • Competitive rates that track market cycles.2

  • Seamless integration with existing trust accounting platforms.


R&T integrates with more than 50 core processors, so a trust company can adopt an insured cash program without disruption. Portals, APIs, and data-exchange tools give trust officers real-time visibility into balances, transactions, and reporting, without manual workarounds.

FDIC-insured cash sweep programs address a trust company’s pressure to protect their customer relationships, help them meet fiduciary obligations3, and generate consistent, predictable funding for the institution. Institutions that adopt these alternatives are better positioned for the next rate shift and for closer regulatory scrutiny of uninsured exposure. Banks with trust departments receive the same benefits.

1 Under the DDM program, funds are deposited into demand deposit accounts (DDAs) or money market deposit accounts (MMDAs) at receiving banks or share draft accounts or share accounts at receiving credit unions. While customers’ funds are held in MMDAs or share accounts, the return of the customers’ funds from the DDM program may be delayed as, under federal regulations, the receiving institution is permitted to impose a delay of up to seven days on any withdrawal request from an MMDA or share account.

2 While interest rates obtained on funds placed at receiving institutions under the DDM program may, under certain circumstances, outperform cash alternatives, such as money market funds, the primary objective of the DDM program is to provide customers with convenient access to expanded deposit insurance coverage on their funds (and not for investment enhancements or higher rates of returns or profits).

3 R&T does not act in a fiduciary or trustee capacity with respect to the DDM program (the “Program”) and makes no representations or warranties that the Program satisfies any investment policy or other requirements for participating institutions. R&T does not represent that the Program enables participating institutions to meet their own fiduciary or other obligations or duties. Participating institutions are solely responsible for complying with all such policies and requirements, as well as any other applicable laws or regulations governing the deposit of specific types of funds into the Program (e.g., qualified retirement funds, free credit balances of brokerage institutions, escrow funds). R&T makes no representations or warranties that the Program complies with any such laws, except to the extent expressly set forth in the written agreements entered into between R&T and the participating institution.

Previous
Next

Media Contact

Melissa Kaiser
Director, Marketing

  • 1-212-830-5242
  • mkaiser@rnt.com

Don’t Miss Out on the Latest Insights.

Follow us on: image/svg+xml

Interested?

Learn how we can help you attract, grow & retain more deposits.

Contact Us

You are now leaving rnt.com

Stay on site

OR

Click to Continue
R&T Logo, White
aba premiere partner logo
great place to work certified, OCT 2026-OCT 2027
  • 1-866-237-2752
  • info@rnt.com
  • 1370 Broadway, 17th Floor
    New York, NY 10018-7302
  • LinkedIn
  • Our Solutions
    • DDM®
    • CDMX®
    • RTID®
    • Funding
  • Who We Serve
    • Depository Institutions
    • Trust Companies
    • BaaS Banks
    • FinTechs
    • Broker-Dealers
  • About R&T
    • Why R&T
    • Events
    • Testimonials
    • Leadership Team
    • Receiving Institution Lists
  • Technology
  • Resources
    • News & Insights
    • Collateral
    • Videos
    • Use Cases
    • Podcasts & Webinars

R&T Deposit Networks, LLC, R&T Deposit Marketplace, LLC, R&T Deposit Solutions, LLC and R&T Deposit Programs, LLC (each d/b/a R&T Deposit Solutions), each a Delaware limited liability company, (together, “R&T”) provide administrative, recordkeeping, and/or other services to banks, credit unions, trust companies, wealth management firms, broker-dealers and other institutions with respect to deposit placement and sweep programs, including the Demand Deposit Marketplace® (DDM®), Certificate of Deposit Marketplace Exchange℠ (CDMX®) and R&T Insured Deposits℠ (RTID®) programs, as well as other services. An affiliate of R&T, Stable Custody Group II LLC (“Stable”), acts as agent of participating sending institutions under the DDM and CDMX programs.  R&T and Stable, together, “we”, “us” or “our”.  All of our services are provided subject to the terms and conditions of the written agreements and/or agency appointments between us and our clients with respect to those services, and we provide no representations or warranties, express or implied, except as expressly set forth in those written agreements and/or appointments. Click here for our legal and other disclosures. We are not an FDIC or NCUA-insured institution. FDIC insurance only covers the failure of an FDIC-insured institution. NCUA insurance only covers the failure of an NCUA-insured institution.  Certain conditions must be satisfied for FDIC and NCUA pass-through deposit insurance coverage to apply. Click here for a list of the FDIC and NCUA-insured institutions with which R&T has a direct or indirect business relationship for the placement of deposits under the DDM, CDMX, and RTID programs, and into which a participating institution may place deposits (subject to the terms of those programs and any opt-outs by the participating institution and/or its customers).  While the DDM, CDMX, and RTID programs provide access to an expanded level of FDIC or NCUA deposit insurance coverage on funds placed into the programs (subject to program terms and applicable laws, regulations and guidance, including pass-through insurance coverage requirements), the DDM, CDMX and RTID programs, themselves, as well as our other service offerings, are not insured or guaranteed by the FDIC or NCUA, are not deposits, and may lose value. We are not an affiliate of an FDIC or NCUA-insured institution, we are not an office, division, or sub-division of the FDIC or NCUA, and we are not associated with the FDIC or NCUA or office, division, or sub-division thereof. The primary objective of the DDM, CDMX, and RTID programs is to provide customers with convenient access to expanded deposit insurance coverage on their funds (and not for investment enhancements, higher rates of returns or profits). R&T®, Reich & Tang®, Demand Deposit Marketplace®, DDM®, DepositView®, CDMX®, and RTID® are registered marks and R&T DirectSM is a pending mark of R&T Deposit Networks, LLC. IDEA℠ , Certificate of Deposit Marketplace Exchange℠ , R&T Insured Deposits℠ and R&T Connect℠ are unregistered service marks of R&T Deposit Networks, LLC.

© 2026 R&T Deposit Networks, LLC

  • Privacy Policy
  • Privacy Policy – CA
  • Terms of Use
  • Legal Disclosures
  • Receiving Institution Lists
  • DDM Program Limit
  • Do Not Share My Personal Information
  • Cookies